Denver Mortgage Broker
Helping You Find the Right Loan
Mortgage Guidance Built Around You
A Mortgage Experience Built Around You
Buying or refinancing a home isn't one-size-fits-all. I take the time to understand your goals, your finances, and what matters most to you before recommending a loan.
As a mortgage broker, I shop multiple lenders and loan programs to find options that fit your specific situation, whether you're buying your first home, moving up, investing, or refinancing.
You'll get straightforward answers, personalized guidance, and a real person in your corner from application to closing.
You'll get straightforward answers, personalized guidance, and a real person in your corner from application to closing.
The Home Loan Process
Get Pre-Approval
We'll review your goals, income, assets, credit, and loan options so you know what you can comfortably afford.
Find the Right Home
Shop with confidence knowing your financing strategy is in place. I'll also coordinate with your real estate agent along the way.
From Contract to Closing
Once you're under contract, I'll guide your loan through processing and underwriting, keep you updated, and help get you to the closing table.
Don't Just Take My Word for It
Mortgage Programs
Explore mortgage options designed around your goals, whether you're buying,
refinancing, or investing.
Home Loan Options
With access to a wide range of loan programs, I’ll help you compare your options and understand the tradeoffs so you can choose the financing that makes sense for you.
Conventional Loans
FHA & VA Loans
First-Time Buyer & Down Payment Assistance
Jumbo Loans
Self-Employed & Non-QM Loans
Investment Property Loans
Mortgage Insights & Resources
The Seller Can Help You Get a Lower Mortgage Rate and Here Is How the Math Actually Works
Seller dollars used for permanent rate buydown lower payments for life. Jennifer Chicano explains when it makes sense. ...more
Mortgage
September 15, 2026•3 min read
What If Home Prices Drop After I Buy and Here Is the Honest Answer Every Buyer Needs to Hear
Nobody times the market perfectly. Jennifer Chicano explains why long term goals beat short term price fears. ...more
Mortgage
September 09, 2026•2 min read
Buyers Are Getting Negotiating Power Back and Here Is How to Use It Before the Window Closes
Longer days on market, price cuts, concessions available. Jennifer Chicano explains how to structure offers now. ...more
Mortgage
September 08, 2026•3 min read
Should You Buy Now or Wait for Mortgage Rates to Drop and Here Is the Honest Answer
Lower rates bring more buyers and higher prices. Jennifer Chicano explains why timing beats rate chasing now. ...more
Mortgage
September 08, 2026•2 min read
You Do Not Need 20 Percent Down to Buy a Home and This Belief Is Keeping Too Many Buyers Waiting
Loan programs, DPA, seller concessions reduce upfront costs. Jennifer Chicano explains your real down payment options. ...more
Mortgage
September 08, 2026•2 min read
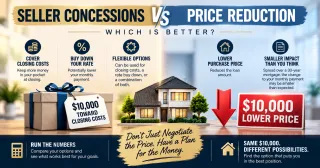
Seller Concession vs Price Reduction Which Is Better and Here Is How to Compare the Numbers First
$10K off price vs $10K toward closing costs math is different. Jennifer Chicano explains when each one wins. ...more
Mortgage
September 08, 2026•3 min read
Frequently Asked Questions
How often can I refinance my mortgage?
It depends on your loan type and the refinance program. Some loans have waiting periods, while others may allow you to refinance sooner. The bigger question is whether refinancing will actually save you money. I’ll help you compare the rate, payment, closing costs, and potential savings to see if the numbers make sense.
Can I buy a home with little or no money down?
Yes, depending on the loan program and your qualifications. Some mortgages offer low or even zero-down-payment options, and down payment assistance may also be available. I’ll help you explore the programs you qualify for and determine which option makes the most sense for you.
How do I know which mortgage is right for me?
The right mortgage depends on more than just the interest rate. Your income, credit, down payment, monthly payment goals, and how long you plan to own the home can all affect which loan makes the most sense. I’ll compare multiple loan options and help you understand the tradeoffs so you can make a confident decision.
How long does it take to get a mortgage?
Most of my home loans close within 2 to 4 weeks, but when timing matters, I can close in as little as 8 business days. Every loan is different, but I stay ahead of the details, communicate throughout the process, and work closely with everyone involved to keep your closing on track.
How do I know if I qualify for a home loan?
Qualifying for a mortgage depends on your income, credit, debts, assets, and the loan program. You don’t need perfect credit or a huge down payment to qualify. I’ll review the full picture and help you understand what options may be available — and if you’re not ready yet, what steps can help get you there.
When does it make sense to refinance a mortgage?
Refinancing can make sense when it improves your overall financial situation. That might mean lowering your payment or rate, changing your loan term, accessing home equity, or consolidating higher-interest debt. I’ll help you run the numbers to see whether the potential benefit outweighs the cost of refinancing.
How much money do I need upfront to buy a home?
The amount you’ll need depends on your loan, down payment, closing costs, and the property you’re buying. Some buyers need much less upfront than they expect, especially with low-down-payment programs, down payment assistance, or seller concessions. I’ll help you estimate the numbers early so you know what to expect before you start shopping.
Can I get a mortgage after bankruptcy?
Yes, it may be possible to qualify for a mortgage after bankruptcy. Waiting periods and requirements vary depending on the type of bankruptcy, loan program, and your financial history since the bankruptcy. I’ll help you understand your options and build a plan for getting mortgage-ready.
When should I lock my mortgage interest rate?
The right time to lock depends on your loan, closing timeline, and what the market is doing. Rather than trying to predict where rates will go next, I’ll help you evaluate the current market and your specific numbers so you can make an informed decision about when to lock.
FREE HOME REPORT
Personalized Insights for Your Home Journey
Whether you own a home or are planning to buy in the future, get personalized market insights and financial tools designed to help you make informed decisions about what comes next.
Mortgage Calculator
Estimate your monthly mortgage payment based on the home price, down payment, interest rate, and loan term.
| Year | Interest | Principal | Balance |
|---|



Copyright 2026. All rights reserved. Jennifer Chicano NMLS #1194079 | Zero Point Mortgage Services NMLS #1216108
Equal Housing Opportunity